Servicios
Descargas
Buscar
Idiomas
P. Completa
Environmental performance as a strategic driver of financial outcomes: A mixed-methods analysis
Marcos Filho Lima Bastos; Clandia Maffini Gomes; Ana Paula Perlin;
Marcos Filho Lima Bastos; Clandia Maffini Gomes; Ana Paula Perlin; Jordana Marques Kneipp; Lílian Caporlíngua Giesta Cabral
Environmental performance as a strategic driver of financial outcomes: A mixed-methods analysis
Desempenho ambiental como driver estratégico do resultado financeiro: Uma análise de abordagem mista
El comportamiento medioambiental como impulsor estratégico de los resultados financieros: Un análisis de enfoque mixto
Contextus – Revista Contemporânea de Economia e Gestão, vol. 23, e95603, 2025
Universidade Federal do Ceará
resúmenes
secciones
referencias
imágenes

Abstract: Background: This study arises from the need to deepen our understanding of the impact of environmental performance on the financial performance of companies in the Brazilian capital market.

Purpose: The general objective of this study was to analyze the influence of the Environment and Climate Change dimensions on the financial performance of companies listed on the Corporate Sustainability Index (ISE).

Method: The study was divided into two methodological phases, descriptive in nature and quantitative and qualitative in approach, respectively. In the quantitative phase of the study, Pearson correlation and multiple linear regression techniques were used. In the qualitative stage, content analysis was carried out on the findings of the semi-structured interviews conducted.

Results: The results of the first phase of the research showed that the performance of the Environment dimension has a positive and statistically significant influence, but with a low magnitude of effect size, on the profitability indicators ROA and ROE of the listed companies. In the second phase of the research, it was identified that managers recognize the impact of environmental management practices on the financial result, highlighting the related risks and opportunities, the organizational image, reputation and competitiveness, as well as the barriers that still exist in implementing more environmentally sound practices integrated with financial aspects.

Conclusions: The study's innovative nature is noteworthy in its proposal to conduct a mixed-approach study with a view to understanding the relationship between environmental and financial performance, an initiative that has been little identified in previous studies. In addition, the companies analyzed belong to the ISE, one of the main benchmarks of the Brazilian capital market.

Keywords: environmental performance, financial performance, corporate sustainability index, climate change, Brazil.

Resumo: Contextualização: Esse estudo emerge da necessidade de aprofundamento da compreensão acerca do impacto do desempenho ambiental no desempenho financeiro das empresas do mercado de capitais do Brasil.

Objetivo: O objetivo geral deste estudo foi analisar a influência das dimensões Meio Ambiente e Mudança do Clima no desempenho financeiro nas empresas listadas no Índice de Sustentabilidade Empresarial (ISE).

Método: O estudo esteve dividido em duas fases metodológicas, de natureza descritiva e abordagens quantitativa e qualitativa, respectivamente. Na fase quantitativa do estudo, foram empregadas técnicas de correlação de Pearson e regressão linear múltipla de dados. Na etapa qualitativa, foi realizada análise de conteúdo nos achados das entrevistas semiestruturadas realizadas.

Resultados: Os resultados da primeira fase da pesquisa evidenciaram que o desempenho da dimensão Meio Ambiente exerce influência positiva e de significância estatística, porém de baixa magnitude de tamanho de efeito, nos indicadores de rentabilidade ROA e ROE das empresas listadas. Na segunda fase da pesquisa, identificou-se que os gestores reconhecem o impacto das práticas de gestão ambiental para o resultado financeiro, com destaque para os riscos e oportunidades relacionados, para a imagem organizacional, reputação e competitividade, bem como para as barreiras ainda existentes na implementação de práticas ambientalmente mais sólidas e integradas aos aspectos financeiros.

Conclusões: Destaca-se o caráter inovador do estudo na proposta de conduzir uma pesquisa de abordagem mista com vista a compreensão da relação entre desempenho ambiental e financeiro, iniciativa pouco identificada em estudos anteriores. Ademais, o recorte de empresas analisadas, pertencentes ao ISE, um dos principais benchmarks do mercado de capitais brasileiro.

Palavras-chave: desempenho ambiental, desempenho financeiro, índice de sustentabilidade empresarial, mudanças climáticas, Brasil.

Resumen: Contextualización: Este estudio surge de la necesidad de profundizar en el conocimiento del impacto del desempeño ambiental en el desempeño financiero de las empresas del mercado de capitales brasileño.

Objetivo: El objetivo general de este estudio fue analizar la influencia de las dimensiones Medio Ambiente y Cambio Climático en el desempeño financiero de las empresas que cotizan en el Índice de Sostenibilidad Empresarial (ISE).

Método: El estudio se dividió en dos fases metodológicas, de naturaleza descriptiva y enfoque cuantitativo y cualitativo, respectivamente. En la fase cuantitativa del estudio se utilizaron las técnicas de correlación de Pearson y regresión lineal múltiple. En la fase cualitativa, se realizó un análisis de contenido de los resultados de las entrevistas semiestructuradas.

Resultados: Los resultados de la primera fase de la investigación mostraron que el desempeño de la dimensión Medio Ambiente tiene una influencia positiva y estadísticamente significativa, pero con una magnitud baja del tamaño del efecto, sobre los indicadores de rentabilidad ROA y ROE de las empresas cotizadas. En la segunda fase de la investigación, se identificó que los gestores reconocen el impacto de las prácticas de gestión ambiental sobre los resultados financieros, destacando los riesgos y oportunidades relacionados, la imagen organizacional, la reputación y la competitividad, así como las barreras que aún existen para implementar prácticas más respetuosas con el medio ambiente e integradas con los aspectos financieros.

Conclusiones: Destaca el carácter innovador del estudio al proponer la realización de un estudio de enfoque mixto con vistas a comprender la relación entre el desempeño ambiental y el financiero, iniciativa poco identificada en estudios anteriores. Además, la muestra de empresas analizadas pertenecía al ISE, uno de los principales índices de referencia del mercado de capitales brasileño.

Palabras clave: Desempeño ambiental, Desempeño financiero, Índice de Sostenibilidad Empresarial, cambio climático, Brasil.

Carátula del artículo

Environmental performance as a strategic driver of financial outcomes: A mixed-methods analysis

Desempenho ambiental como driver estratégico do resultado financeiro: Uma análise de abordagem mista

El comportamiento medioambiental como impulsor estratégico de los resultados financieros: Un análisis de enfoque mixto

Marcos Filho Lima Bastos
Federal University of Rio Grande do Sul (UFRGS), Brasil
Clandia Maffini Gomes
Institute of Administration Foundation (FIA), Brasil
Ana Paula Perlin
Federal University of Santa Maria (UFSM), Brasil
Jordana Marques Kneipp
Federal University of Santa Maria (UFSM), Brasil
Lílian Caporlíngua Giesta Cabral
Federal Rural University of the Semi-Arid Region (UFERSA), Brasil
Contextus – Revista Contemporânea de Economia e Gestão, vol. 23, e95603, 2025
Universidade Federal do Ceará

Recepción: 23 Junio 2025

Aprobación: 14 Agosto 2025

Publicación: 24 Septiembre 2025

1 INTRODUCTION

Recent environmental issues highlight the need to reflect on the true value of nature in the financial discussions and strategies of the global corporate environment (United Nations Brazil, 2021). To this end, integrating companies’ environmental and financial objectives represents a strategic pillar for Sustainable Development (SD), as it enhances Environmental, Social, and Governance (ESG) reporting, generates new revenue streams, and optimizes managerial processes. When combined, these factors foster socio-environmental development, which in turn significantly contributes to corporate SD (Bodgan et al., 2023).

Integrating environmental and financial objectives in the corporate context has the potential to promote long-term sustainability, improve corporate image, and strengthen relationships with the various stakeholders involved in decision-making processes, while also opening opportunities to access new markets and business prospects (Lutzer et al., 2024).

Despite evidence of the importance and critical role that integrating environmental and financial objectives plays in SD, understanding the effects of adopting environmentally oriented practices on companies’ financial performance remains the subject of diverse and sometimes divergent discussions. Some studies point to results supporting the notion that adopting sustainable practices positively influences financial performance (Feng et al., 2018; Garcia et al., 2022; Li et al., 2017; Xie et al., 2019), whereas others find no relationship between these constructs (Lima et al., 2022; Lucato et al., 2017) or even report a negative relationship between environmental performance, based on the preservation of natural resources, and financial performance, which is built from the perspective of profit and return on capital (Baah et al., 2021; Grisales & Caracuel, 2021).

The notion that the value of organizations, for both the market and society, goes beyond the benefits derived from transforming, producing, or delivering goods and services stems from a turbulent global scenario that increasingly demands the adoption of sustainable strategies by companies. Sustainability indices have emerged as a response to the need to quantify SD, providing greater transparency to the capital market (Guirk & Downling; Carr, 2019; Zago et al., 2018).

Within this context, the Corporate Sustainability Index (ISE) has stood out among Brazilian sustainability indices (B3 S.A., 2023). In light of the above, the general objective of this study is to analyze the influence of environmental performance on financial performance, focusing on companies listed in the ISE between 2022 and 2024. Accordingly, the specific objectives are to investigate whether there is a correlation between the scores for the Environment and Climate Change dimensions and financial performance; to assess the influence of environmental performance on financial performance; and to explore the perceptions of managers from ISE-listed companies regarding the impact of environmental performance on their organizations’ financial outcomes.

This study has the potential to expand understanding while seeking to help reconcile and reduce the divergences surrounding this topic. In particular, in the context of the Brazilian capital market, it aims to provide practical and theoretical insights that may encourage practices more closely aligned with companies’ environmental and financial objectives.

Despite the growing discussions on ESG and the capital market, gaps remain in understanding the mechanisms and extent to which environmental performance affects corporate financial outcomes. By integrating quantitative and qualitative approaches, this study aims to address the gap identified in the international literature regarding the impact of environmentally oriented practices on the financial results of large companies, with an emphasis on those listed in the ISE, one of the main benchmarks of the Brazilian capital market. In doing so, it contributes to advancing the knowledge frontier on the impact of environmental performance on financial performance, particularly in the context of emerging markets.

The contributions of this study therefore encompass both theoretical and practical aspects that may strengthen the understanding of the relationship between environmental and financial performance in the corporate context analyzed and in similar contexts. As an innovative potential for the scientific field, the study proposes to integrate quantitative and qualitative approaches to better understand the interaction between the constructs of environmental performance and financial performance, an initiative seldom identified in previous studies. The following section presents the theoretical framework of the study.

2 THEORETICAL FRAMEWORK

This theoretical framework section has two main purposes. The first is to understand the most common metrics used to measure environmental and financial performance in national and international academic contexts. The second is to develop the research hypotheses, based on the discussion regarding the relationship and influence that environmental performance exerts on financial performance. Recent literature presents different metrics for measuring environmental and financial performance. Regarding financial performance, studies have focused on analyzing profitability and return indicators, such as Return on Assets (ROA), Return on Equity (ROE), Return on Invested Capital (ROIC), Gross Profit Margin (GPM), Net Profit Margin (NPM), and EBITDA Margin (MEBITDA) (Castilho & Barakat, 2022; Grisales & Caracuel, 2021; Lima et al., 2022; Lucato et al., 2017; Severo et al., 2017; Sobrosa et. al., 2020).

Other studies, in addition to using indicators, have measured financial performance through the values of balance sheet accounts, with emphasis on equity, or through income statement accounts, prioritizing sales revenue (Castilho & Barakat, 2022; Garcia et al., 2022; Lucato et al., 2017). Attention has also been given to cost reduction and debt levels among financial performance metrics (Almada et al., 2022; Kouloukoui et al., 2018; Severo et al., 2017). Overall, categorically different metrics have been used, whether profitability, return, or indebtedness indicators, balance sheet or income statement accounts, shareholder behavior, among others, which in some studies were applied jointly, revealing the breadth of variables considered for measuring financial performance.

Regarding environmental performance, studies have focused on greenhouse gas (GHG) emission levels (Garcia et al., 2022; Kouloukoui et al., 2018), performance in the Corporate Sustainability Index (ISE) (Almada et al., 2022; Castilho & Barakat, 2022; Pereira et al., 2020), productive and energy efficiency, and environmental resource management (Severo et al., 2017), among others. In addition, some studies have conducted independent sample analyses based on the portfolios of B3 S.A.’s sustainability indices, such as the ISE and ICO2, comparing the financial performance of companies listed in these portfolios with those not listed, using participation in these indices as the metric for the environmental construct (Lima et al., 2022; Sobrosa et al., 2020). Qualitative studies have mostly relied on literature reviews, documentary analyses, and interviews with managers and employees regarding their perceptions of the relationship between financial and environmental performance (Almada & Borges, 2018; Melo et al., 2019; Moçato et al., 2019).

As for specific analyses of the relationship between environmental and financial performance among companies listed in the ISE, a stronger debate was identified between the existence of a positive relationship and the absence of a relationship between the constructs in this context, which is consistent with the general findings of the conducted systematic literature review. Lucas, Yoshikuni, and Augustini (2022) examined the causal relationship between the ISE and the Ibovespa market using causality tests and regression models. Their results indicated a bidirectional causal relationship, suggesting that the rise or fall in the returns of assets linked to the ISE can be considered a predictor of the overall performance of assets traded on the stock exchange, as well as the inverse relationship.

Supporting findings that point to a positive relationship between the constructs, Silva and Lucena (2019) analyzed the relationship between participation in the ISE and profitability over the period 2010–2016, using regression models. Their results showed a positive relationship between participation in the ISE and ROA. With the same purpose as Silva and Lucena (2019), Monteiro, Santos, Leite, and Santos (2021) sought to determine whether economic-financial performance is influenced by adherence to the ISE, considering both participating and non-participating companies, as well as the duration of their participation in the index. Their results indicated that companies listed in the ISE had higher performance in profitability indicators. Calda et al. (2021) followed a similar approach, aiming to identify the relationship between sustainability classification—using ISE participation as the criterion—and the liquidity of listed and non-listed companies. They applied statistical tests to assess data from 2012 to 2016, and their results showed greater liquidity and better working capital management among participating companies.

Overall, there is a prevalence of studies that, when aiming to analyze the relationship between environmental and financial performance of companies participating in the ISE, adopted a comparative analysis strategy between listed and non-listed companies. This predominant decision is likely justified by the relatively small number of listed companies, given the emerging nature of sustainability indices in the national context, which makes it difficult to conduct analyses without incorporating other scenarios into the assessment. In the broader scope of studies, the debate over the existence and direction of the relationship between the constructs must take into account different contexts whether corporate, economic, or sectoral as well as the metrics used to measure the variables and the methodological aspects. Without delving into detail, there is a predominance of findings that establish a positive relationship between the constructs, as opposed to negative or non-existent relationships. Based on the evidence of a positive relationship between environmental and financial performance, the hypotheses for the quantitative stage of this research are proposed.

H1: The environmental and financial performance of companies listed in the ISE are significantly and positively related.

H2: Environmental performance has a significant and positive impact on the financial performance of companies listed in the ISE.

The following section presents the methodological procedures of the study.

3 METHODOLOGY

This research can be characterized as descriptive in terms of its objectives and as employing both quantitative and qualitative approaches in terms of its methodological procedures. The following section presents the research phases in detail.

3.1 Descriptive phase with a quantitative approach

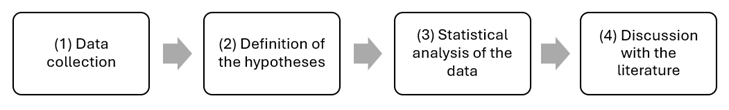
This phase aimed to support the achievement of the specific objectives of verifying the existence of a correlation between the scores for the Environment and Climate Change dimensions and financial performance, as well as assessing the influence of environmental performance on financial performance. Figure 1 illustrates the stages of this research phase.


Figure 1
Stages of the quantitative phase
Source: Developed by the authors.

The data collected consisted of the score reports of companies participating in the ISE from 2021 to 2023, provided by the ESG Workspace platform of the Brazilian Stock Exchange, as well as the structured performance reports of these same companies issued by their management as part of the Standardized Financial Statements.

The analysis covered all organizations listed in the ISE during the study period that, in the same period, had Standardized Financial Statements available for public access on the B3 S.A. platform. Out of a total universe of 252 companies, 228 were analyzed and 24 were excluded. Specifically, the Balance Sheet (BS) and the Income Statement (IS) were used to calculate the profitability and return indicators, as these documents contain the necessary accounts for the calculations. Figure 2 presents the conceptual theoretical model for the quantitative stage of the research.

The study’s hypotheses were developed based on the literature review. During data analysis, Pearson’s correlation analysis was applied between the environmental variables performance in the ISE’s Environment and Climate Change dimensions and the financial variables, consisting of profitability indicators, namely Return on Assets (ROA), Return on Equity (ROE), and Return on Investment (ROI), and profitability margins, namely Net Profit Margin (NPM), Gross Profit Margin (GPM), and Earnings Before Interest, Taxes, Depreciation, and Amortization Margin (MEBITDA). The magnitude of the correlations was measured according to the categorization by Schober, Boer, and Schwarte (2018). It is important to emphasize that analyzing “relationships” does not necessarily imply establishing “causality” between variables (Schmuller, 2019).

In a second step, multiple linear regression was performed to assess the influence of environmental variables (independent or predictor variables) on financial variables (dependent or outcome variables). The steps for performing the multiple regressions are presented in Figure 2.


Figure 2
Technical procedures (multiple regressions)
Source: Developed by the authors.

The first five steps refer to the identification of potential statistical issues in the variables. In Step 1, the standard error of the regression coefficients was calculated using bootstrapping resampling (2,000 resamples, 95% CI), with the parameters package (Lüdecke & Patil, 2020) in R software. Bootstrapping is a robust procedure for deviations from residual normality or heteroscedasticity in the regression model (Haukoos & Lewis, 2005). Step 2 aimed to identify significant outliers in the model using Cook’s method (threshold = 0.8). Step 3 involved calculating the Tolerance Index (1–R²) to verify the existence of multicollinearity among the independent variables. Step 4 sought to assess the presence of residual correlation (Durbin–Watson coefficient). In Step 5, the model was tested for heteroscedasticity. The final step consisted of performing the multiple regressions.

After the statistical analysis of the data, the study’s findings were discussed in light of the available literature. The discussion addressed the overall impact of environmental performance on financial performance. The specific analysis examined the impact by environmental dimension of the ISE and by the accounting-financial indicator used. The following section presents the second phase of the study.

3.2 Descriptive phase with a qualitative approach

To address the specific objective of understanding managers’ perceptions regarding the relationship between environmental and financial performance in organizations, this phase of the study consists of conducting semi-structured interviews with managers from the listed organizations. The development of the interview guide was based on the literature review previously conducted in this study, aiming to support the constitutive and operational definitions. The former focuses on defining the phenomenon, while the latter emphasizes how the phenomenon in question manifests itself. Based on these definitions, the interview guide topics were generated and organized according to theoretical categories of analysis. The interview guide is provided in the appendices of this research. Table 1 presents the categories of analysis by constitutive definition, along with the topics investigated in this stage.

Table 1
Categories of analysis and study topics.

Source: Developed by the authors.

The items of the interview guide were developed considering the target audience of the research, namely the managers to be interviewed, using language that was as appropriate, clear, and direct as possible. After being developed, the items were submitted for evaluation by three judges, a methodologically adequate number for instrument validation (Cassepp-Borges et al., 2012). The criteria for selecting the judges, who were experts in the subject matter, were as follows: a doctoral degree in Administration or Accounting Sciences, with research and publications in academic journals in the field of socio-environmental management.

Invitations to participate were sent via email to all organizations included in the ISE portfolios from 2022 to 2024. Given that this stage of the research directly involves human participants in this case, the managers of the organizations studied a series of ethical measures was adopted, starting with the request for consent to conduct the interviews, documented through the Informed Consent Form (ICF). The interviews were conducted and recorded remotely via the Google Meet platform.

For the interview analysis, the content analysis technique proposed by Moraes (1999) was applied, which describes an approach for analyzing and interpreting verbal and non-verbal content. This research was approved by the Ethics Committee of Plataforma Brasil – Universidade Estadual do Rio Grande do Norte (UERN), under opinion no. 7,045,438 dated August 31, 2024. The following section presents the analysis and discussion of the research results.

4 ANALYSIS AND DISCUSSION OF RESULTS

This section on analysis and discussion of results is divided into two distinct parts. First, the quantitative analysis of the relationship and influence of the environmental dimensions of the ISE on the financial indicators of companies listed in the index is presented, employing Pearson’s correlation and multiple linear regression techniques. Next, the qualitative stage of the study is discussed, based on the analysis of the interviews conducted with managers of companies listed in the ISE. Finally, the study’s final conclusions regarding the results are presented.

4.1 Quantitative Analysis of the Influence of Environmental Performance on Financial Performance

This section presents the quantitative analysis of the relationship between environmental and financial performance, using as environmental variables the performance in the ISE’s Environment and Climate Change dimensions, and as financial variables the profitability indicators (ROA, ROE, ROI) and profitability margins (NPM, GPM, MEBITDA), covering the period from 2021 to 2023. First, the correlations between the variables are presented, followed by sections with multiple linear regression models, and finally, the analysis and discussion of the results.

4.1.1 Correlation Analysis between Environmental and Financial Variables

The purpose of the correlation analysis is to meet the specific objective of verifying the existence of a correlation between the scores for the Environment and Climate Change dimensions and financial performance. Table 2 presents the correlations between the variables. The categorization of correlation strength was based on the classification proposed by Schober, Boer, and Schwarte (2018). To control the Type I error rate (false positives), Holm’s post hoc adjustment was applied.

Table 2
Pearson correlation analyses between environmental and financial variables

Source: Research data.Note: * = p < 0,05; ** = p < 0,01.

Based on the correlation coefficients (r), the environmental variables showed a positive and significant association of weak magnitude only with the financial indicator ROE (Environment: r = 0.29, p < 0.01; Climate Change: r = 0.20, p < 0.01), with no other statistically significant correlations identified between the financial and environmental variables. Moreover, most financial indicators were found to be correlated with each other, as were the environmental variables, which showed a positive correlation of moderate magnitude (r = 0.42, p < 0.01). Thus, H1 of this study was partially confirmed, indicating a positive and statistically significant relationship between the environmental dimensions of the ISE and a single financial indicator, ROE.

The low magnitude of the correlation identified, as well as the absence of statistical significance between the performance of the environmental dimensions and the other financial indicators, may be associated with temporal gaps in the relationship between these variables. This suggests that the relationship may not necessarily manifest simultaneously, meaning that variations in environmental performance may be reflected in financial performance over longer periods. This may also indicate an emerging nature, in many respects, of the relationship between financial and environmental performance, a pattern also observed in recent systematic and comprehensive reviews of the international literature (Chowdhury et al., 2023).

4.1.2 Impact of the performance in the Environment and Climate Change dimensions on Return on Assets (ROA)

The results of the multiple linear regression analysis (enter method) for the first regression model, which used the financial performance variable ROA as the dependent variable (DV) and the performance in the Environment and Climate Change dimensions as the independent variables (IVs), considering a 5% significance threshold for p, showed no statistically significant influence of the performance in the Environment and Climate Change dimensions on the ROA of the listed companies (F(2, 225) = 2.58, p > 0.05; R2adjusted = 0,014).

Furthermore, based on the Coefficient of Determination (R²), it is estimated that only 1.4% of the variation in ROA performance can be explained by the scores of the Environment and Climate Change dimensions of the ISE. Table 3 presents the coefficients for all predictors.

Table 3
Predictor variables of the financial performance variable ROA

Source: Research data.Note: * = p < 0,05; ** = p < 0,01.

Despite the absence of a statistically significant influence of the model, the dimension-level analysis revealed a statistically significant and positive influence of the Environment dimension on the ROA of the companies analyzed, indicating that a 1-point increase in the Environment IV leads to a 7.07-point increase in ROA (Environment: b = 7.07, p < 0.05).

Regarding the influence of environmental variables on financial indicators, it should be noted that the model as a whole, which incorporates the Climate Change dimension, did not present statistical significance, indicating no impact of the combined effect of the dimensions on corporate financial performance. Current climate challenges are urgent and unprecedented, and corporate strategies have not demonstrated sufficient capacity to address this global problem (Braunerhjelm & Hepburn, 2023).

The difficulty in consolidating effective practices aimed at reducing GHG emissions and consequently decreasing the frequency and intensity of climate change effects is linked to the growing global patterns of consumption, which increasingly demand higher levels of production and the supply of goods and services. In addition, emphasis on improving corporate practices for climate change mitigation has focused on energy transition, which, according to recent evidence, has not shown sufficient capacity to meet the rising demands of production (Arteaga et al., 2023; Murphy, 2024).

Efforts to improve resource efficiency, including those present in the ISE’s main environmental performance practices such as water and energy management, as a strategy to address global warming, may produce an adverse effect. This occurs when focus is shifted away from reducing consumption patterns toward seeking the use of clean energy, which remains insufficient to meet global consumption standards, potentially encouraging increased demand justified by the energy transition (Arteaga et al., 2023; Murphy, 2024).

Conversely, the individual, positive, and significant impact of the Environment dimension (Environment: b = 7.07, p < 0.05), which has a broader environmental scope, may indicate that corporate investment in improving water, energy, and waste management strategies, along with other environmental management practices, positively influences the efficiency of asset utilization measured by the ROA performance indicator. Superior environmental performance can positively affect asset use efficiency, and consequently ROA, through a range of mechanisms, with particular emphasis on resource use efficiency (McCarthy et al., 2010; Wang et al., 2024; Zhang, 2021).

4.1.3 Impact of performance in the Environment and Climate Change dimensions on Return on Equity (ROE)

Unlike the first case, the results of the multiple linear regression analysis (enter method) for the second regression model, which used the financial performance variable ROE as the dependent variable (DV) and the performance in the Environment and Climate Change dimensions as the independent variables (IVs), also considering a 5% significance threshold for p, revealed a statistically significant joint influence of the environmental dimensions on the ROE of companies listed in the ISE (F(2, 225) = 11.60, p < 0.01; adjusted R² = 0.085). Based on the Coefficient of Determination (R²), it can be inferred that 8.53% of the variation in ROE performance can be explained by the scores of the Environment and Climate Change dimensions. Table 4 presents the coefficients for all predictors.

Table 4
Predictor variables of the financial performance variable ROE

Source: Research data.Nota: * = p < 0,05; ** = p < 0,01.

As in the previous case, only the Environment dimension showed a significant and positive influence on the financial variable ROE. It was found that a 1-unit increase in the performance of the Environment IV leads, on average, to a 13.99-unit increase in ROE performance (Environment: b = 13.992, p < 0.01). The findings from this stage of the study indicate that the environmental dimensions significantly and positively affect only specific financial indicators. This can be explained by the fact that financial indicators represent different aspects of financial performance, which is a broader concept. Thus, H2 of this study was also partially confirmed.

The dimension-level analysis showed that this influence stems from the impact of the Environment dimension on the ROE of listed companies. As will be shown below, the other profitability and return indicators did not demonstrate a significant effect from the environmental performance dimensions of the ISE. The impact of environmental performance on the ROE indicator, as opposed to the absence of impact on ROI (a return indicator) and on the three profitability indicators analyzed, can be explained by the nature of these financial variables and the characteristics of the practices considered in measuring environmental performance by the ISE, as detailed below.

ROE is directly related to equity, whereas ROI and profitability indicators use revenue or total assets as the denominator. Therefore, considering that the ISE’s environmental criteria focus on resource-use efficiency and cost reduction rather than revenue generation, the impact on ROE which is directly influenced by equity, a balance sheet account directly associated with net income (profit or loss) can be justified (Cornellissen & Mukwarami, 2024).

Moreover, although the other indicators are also associated with shareholders, ROE is directly linked to investors’ decision-making process, as it reflects the relationship between equity (investors’ capital) and profit generation (return on shareholders’ invested capital), metrics that are associated with corporate environmental performance and environmental management practices in general (Cornellissen & Mukwarami, 2024). It is also noteworthy that the influence of environmental performance on ROE was found in other recent studies analyzing the impact of environmental dimensions on corporate financial performance (Ismail & Azman, 2024).

The findings from this stage of the study reinforce evidence from previous research, initially by aligning with most studies on the relationship between financial and environmental performance, showing that it is profitable for companies to improve their environmental management practices. However, despite this, the influence of environmental practices on financial performance does not reveal consensual results and remains subject to divergences (Baah et al., 2021; Grisales & Carucael, 2021; Xie et al., 2019; Feng et al., 2018; Li et al., 2017; Donohue & Torugsa, 2016; Cavaco & Crifo, 2014; Endrikat et al., 2014).

It can therefore be stated that the financial and environmental performance of companies listed in the ISE are indeed related and that, while considering the specific nature of each financial and environmental indicator, environmental performance has a significant impact on corporate profitability. Environmental performance affects profitability through a series of mechanisms, including improving levels of green innovation, reducing financing constraints linked to environmental issues, increasing revenue, and enhancing competitiveness and reputation. Companies that achieve superior environmental responsibility performance can increase profitability by attracting investors and consumers through an improved corporate image (Hu & Zhao, 2024).

Nevertheless, the low magnitude of the correlation coefficients and determination coefficients indicates that the explanatory power of environmental performance for financial performance remains incipient, once again revealing the complex and, in many respects, emerging dynamic of seeking harmony between profit generation and environmental protection. The other regression models, considering the financial indicators ROI, NPM, GPM, and MEBITDA, did not show significant results. The low explanatory power of environmental variables over financial variables may indicate an emerging scenario in which environmental performance has not yet fully demonstrated its capacity to influence corporate financial outcomes. In a broader scope, it may also reflect the global corporate context, which is still striving to reconcile financial objectives with environmental preservation, a complex task surrounded by debate and contradictions.

4.2 Qualitative analysis of the influence of environmental performance on financial performance

This stage of the study aims to address the final specific objective of the research, namely to understand managers’ perceptions regarding the impact that environmental performance has on the financial performance of organizations. Two interviews were conducted with managers from two different companies listed in the ISE. Unlike what occurs in a quantitative approach, the qualitative approach has broad discussions across various fields of knowledge about whether the number of participants is “sufficient” to achieve the study’s objectives, the so-called sampling size. The first relevant point to revisit concerns generalization. Very often, demands for a larger number of participants are linked to the positivist perspective of seeking some type of generalization. However, disregarding other specific characteristics of the study beyond the number of responses runs counter to the intrinsically contextual nature of qualitative research (Creswell, 2007; Sim et al., 2018).

Another point of discussion is saturation. In a recent study in the health field, Ahmed (2025) addressed the factors affecting saturation in qualitative research sample size, identifying, among others, the purpose of the study, research design, and time and resource constraints. Thus, it is relevant to outline the reasons supporting the adequacy of conducting two interviews with managers in this stage of the study. Naturally, as this is a mixed-methods study, the present article needed to incorporate qualitative assumptions, and the decision regarding the number of participants was informed by the discussions briefly revisited here. The qualitative phase was complementary to the quantitative phase, and given the complexity of the total dataset compiled, the number of participants for this complementary stage was deemed satisfactory. The interview analysis is divided into two distinct parts. First, general information about the companies and the interviewees is presented, with careful attention to preserving anonymity. This is followed by a discussion of the findings from this stage of the study.

4.2.1 General Information

The first participating company was listed in the ISE during the years 2021 and 2022. It belongs to the Basic Materials/Chemicals/Petrochemicals sector classification, with its main activity being the production of chemical products and an annual revenue in the 2023 fiscal year exceeding seventy billion Brazilian reais. For all purposes, it will hereafter be referred to as Company “A”.

The second company was listed in the ISE throughout the entire analysis period, from 2021 to 2023. It belongs to the Communications/Telecommunications sector classification, with its main activity being the provision of telecommunications services and an annual revenue in the 2023 fiscal year exceeding fifty billion Brazilian reais. It will be referred to as Company “B” in the reporting of results. The summarized data are presented in Table 5.

Table 5
Summary of companies participating in the qualitative stage

Source: Research data.* Values in R$ 1,000 (thousand Brazilian reais), rounded to three decimal places. The values are presented approximately in millions of Brazilian reais to preserve the anonymity of the companies.

As shown in Table 5, both companies recorded annual revenues in the tens or hundreds of billions of Brazilian reais throughout the analysis period, with Company A reporting losses in the last two fiscal years and Company B reporting profits throughout the entire period. Table 6 presents a summary of the interviewees. For all purposes, the interviewee from Company A will be referred to as Interviewee A, and the interviewee from Company B as Interviewee B.

Table 6
Summary of interviewees

Source: Research data.

The following section of the study will present managers’ perceptions regarding the relationship between environmental and financial performance, the impact of environmental performance on financial performance, the controls used to assess financial and environmental performance, financial performance as a determining factor in setting the level of environmental investments, and the importance of financial viability in decisions on environmental investments.

4.2.2 Managers’ perceptions of the impact of environmental performance on corporate financial performance

Initially, the interviewees were asked about their perception of the relationship between financial and environmental performance in the corporate context. Interviewee A expressed the view that, during the processes carried out by companies, environmental, social, and economic impacts are interconnected, demonstrating a belief that corporate processes have both positive and negative impacts on the environment, on society, and on the economic situation of companies, as evidenced in the following transcript:

Interviewee A: “Look, they are completely related because nowadays, when you are carrying out any activity or process, it has positive and negative impacts economic, environmental, and I would also say social so there is no way to separate them.”

In line with Interviewee A’s response, Interviewee B stated that they consider financial and environmental performance to be related and that making the effects of this relationship tangible is a challenge for the corporate environment today, as shown in the following excerpt from the interview:

Interviewee B: “Yes, I think the challenge for all companies today, and for sustainability areas in general, is to be able to make this tangible for the company. But internally, we already have cases of both cost reduction and revenue generation linked to improvements in our overall sustainability agenda, including environmental issues.”

Interviewee B provides a series of examples that highlight the relationship between financial and environmental performance, citing cost reduction and revenue generation. Furthermore, by pointing out the tangibility of the effects of the relationship between financial and environmental performance as a challenge for the corporate environment, Interviewee B presents a view that reflects one of the motivating factors for this study—the uncertainties that still surround the impacts of environmental performance on financial performance. Such uncertainties may stem from successive subjective narratives that have contributed to inconsistencies in the findings on this relationship, creating challenges for companies in quantifying this impact and in understanding the complex nature of tangible financial results that arise from, or are partially influenced by, environmental initiatives (Amarasuriya et al., 2024).

The challenges to making this relationship tangible include a variety of factors, ranging from the lack of standardization in environmental reporting which hinders comparisons between different companies to the high costs of implementing structured environmental management practices, low awareness in many cases, and difficulties in communicating the benefits of environmental investments to the various stakeholders involved (Harif & Natasha, 2024). Moreover, environmental performance may, in the short term, generate costs that outweigh immediate financial benefits, which only become more tangible in the long term. This makes it even more difficult to demonstrate these benefits at the outset (Zhang & Chen, 2017).

The second question asked the interviewees about the impact of environmental performance on financial performance, specifically whether improvements in environmental performance could lead to improvements in financial performance. Both interviewees stated that they believe enhanced environmental performance can positively impact financial performance, as evidenced in the following transcripts:

Interviewee A: “Naturally, because, well… inevitably… this result comes, even helping, you know, the business to endure. […] Society itself, the client, the consumer, ends up becoming more discerning and begins to include these criteria in their choices of products and services. So naturally, when you improve your environmental performance and make this clear, associating it with your product or service, the financial return certainly follows.”

Interviewee B: “Yes, we go from a stage that I think is where most companies began working, which is mitigating legal and regulatory risks… and all of these are linked to some financial figure due to fines or compliance adjustments. So, for us, there is already a high level of maturity in this area.”

Despite agreeing on the positive impact of environmental performance on financial performance—a perception that corroborates the quantitative stage of this study—the interviewees attribute this influence to different aspects. Interviewee A, focusing on external factors to the company, emphasizes the role of environmental practice disclosure in improving corporate image, with subsequent financial gains resulting from enhanced reputation and added value of products. This finding is consistent with Legitimacy Theory, which encompasses a body of studies showing that the pursuit of legitimacy through environmental disclosures has effects on financial performance (Gholami et al., 2022; Lee & Raschke, 2023).

Interviewee B, in turn, highlights aspects more related to internal factors within the organization, such as the mitigation of regulatory risks and the financial benefits of adopting circular economy practices and energy transition initiatives, both associated with the ISE environmental dimension. As evidenced in the document analysis stage of this study, circular economy practices and the pursuit of energy transition are fundamental factors for corporate environmental performance, with significant effects on financial performance (Guirk et al., 2019; Liu et al., 2018).

When asked how corporate policies focused on the environmental agenda take financial aspects into account, the interviewees presented an integrated view of financial aspects and environmental policies. Interviewee A emphasized the need to integrate the environmental agenda into the business strategy, stating that only in this way can financial aspects be properly related.

Interviewee A: “The company will consider financial aspects in the environmental agenda when this environmental agenda is part of the business strategy. The company has only one strategy the business strategy. Sometimes we say there is a sustainability strategy, but that needs to be corrected because there are not two strategies in a company; it makes no sense. When you talk about a sustainability strategy, you are talking about the sustainability aspects and attributes of your business strategy. […] So today, a robust strategy given that studies already show that the impact of climate risks will be one of the most relevant impacts in the short term and is already materializing when thinking about economic performance, must identify these impacts as well as the opportunities. And, as with any strategic planning process, it must calculate the potential positive and negative impacts and incorporate them into the strategy.”

Interviewee A emphasizes the importance of a business strategy that incorporates environmental aspects so that environmental performance can be assessed in an integrated manner with the company’s financial performance. He also states that robust business strategies consider environmental and financial aspects within a single planning process, as it is not feasible to address them separately.

Business strategies that integrate environmental and financial aspects into business decision-making gain a competitive advantage, improving environmental performance with positive effects on corporate financial performance, business sustainability, market value, and long-term profitability (Tan et al., 2022). Corporate sustainable development is directly associated with the capacity of corporate management systems to integrate environmental and financial criteria (Hristov et al., 2022).

Similarly, the statements of Interviewee B align with those of Interviewee A, treating financial aspects as being “linked” to corporate environmental policies, with emphasis on the risks and opportunities arising from this complex dynamic, which is fundamental to the survival of companies.

Interviewee B: “Yes, we will have policies that are indeed tied to indicators that will directly impact the financial side. […] For example, when we look at our environmental policies, all of them address risks and opportunities, and for us, all financial aspects are linked to risks and opportunities. So, our own governance policies include risk management, in which we also estimate the financial impacts of risks and opportunities, and today sustainability is included as a criterion within this framework. […] So, to summarize, this exists both within specific sustainability policies and within processes that are transversal across the company.”

Interviewee B shows that financial aspects are considered in corporate environmental policies insofar as the risk and opportunity analyses of these policies are directly associated with financial matters, and that sustainability itself is a criterion in estimating the financial risks and opportunities within the company’s governance policies. There is empirical evidence regarding the impact of environmental performance on production costs, business value, and returns, which are associated with a range of risks and opportunities (Gasbarro et al., 2017).

In the second question of this stage of the interview, respondents were asked whether the company had controls in place capable of assessing the relationship and impact between financial and environmental performance. Both interviewees stated that such controls exist within their companies. Interviewee A cited as an example the internal pricing of carbon emissions as a way of preparing for the future regulatory environment.

Interviewee A: “For example, in our investments related to climate and emissions, we have an internal carbon pricing process. So, we look at the entire process whether it increases or reduces emissions and when we calculate the NPV, we assess how many emissions it reduces. We have an internal price because it is a way to prepare for the future regulatory environment. So, we are already preparing along those lines, because if you want to think about the perpetuation of your business in the medium and long term, you need to have a strategy that takes these aspects into account.”

Meanwhile, Interviewee B provided three distinct examples: process digitalization, equipment recycling, and improvements to site systems. Subsequently, Interviewee B highlighted the integration of environmental and financial objectives as a strategic pillar of the company in which they work, with emphasis on the financial results arising from initiatives that are, in essence, environmental in nature.

Interviewee B: What I find interesting in this regard is that these are projects with a huge socio-environmental context, but when they go to the SDG, they are 100% business what the project is and what efficiency it is delivering. That is why I distinguish it, because it is much closer to the answer you want. It is not a department trying to show benefits for itself in relation to a socio-environmental project; it is the business area itself quantifying and monitoring this. So, it is finance driving this agenda.”

From the opening excerpt of Interviewee B’s statement, it is evident that the topic carries a certain sensitivity, while there is already recognition of the financial impact of these practices, as demonstrated by the experienced financial benefits of the environmental initiatives mentioned. Furthermore, in Interviewee B’s view, although these initiatives have a significant positive socio-environmental impact, for corporate governance policies they are purely business, with the primary assessment focusing on the financial benefits derived from these programs. The financial results are quantified and monitored, even though their initial scope has an environmental prerogative as its justification.

The statements of both interviewees, particularly those of Interviewee B, show that the environmental agenda in the organizational context goes beyond socio-environmental issues and also represents opportunities for generating financial benefits. This once again corroborates studies that indicate a positive relationship between these constructs and highlights the central role of environmental management in today’s business landscape (Feng et al., 2018; Garcia et al., 2022; Li et al., 2017; Xie et al., 2019).

Finally, the interviewees were asked to assess the importance of environmental investments for the company and, if possible, to comment on notable environmental investments. Interviewee B had already mentioned a series of initiatives, while Interviewee A presented initiatives of high environmental value and with financial impacts that are currently being developed by the company, followed by a brief reflection on the importance of these initiatives by Interviewee B.

Interviewee A: “Right, look… here within our business, and since we are in the plastics value chain, our top priorities are related to climate and post-consumption waste, oceans, plastics, and so on. So, we have been investing specifically in advancing plastics management along the value chain, even creating new recycling businesses that enable the practice of recycling mechanical, energy, and chemical recycling. […] Regarding climate, we also have a series of actions to reduce our environmental footprint. We have a commitment to be carbon neutral by 2050, and we are one of the world’s largest producers of sugarcane-based polyethylene. So, we are investing in evaluating our portfolio to transition from fossil-based to renewable sources, precisely as a strategy for ensuring the perpetuation of the business.”

Interviewee B: “When a company engages in more sustainable actions, even if it is not the silver bullet, ‘Oh, the ISE is not the silver bullet for what makes a company sustainable’ the same will happen with regulation. But when it joins this broader agenda, it is able to focus much more and understand how much it can achieve. Having a robust sustainability strategy will precisely shift its power within its sphere of influence, and I think this is the key point: the moment when all those investments, which often may seem to be for the product itself or for shareholder returns, start to gain layers of impact on economic development, sustainable development, and, indeed, even if the company does not change its business model, it is able to understand and enhance what has a positive impact for it and justify that investment which I believe is the big difference.”

These final responses show that companies have made positive progress in implementing and recognizing the importance of the environmental agenda for the sustainability and perpetuation of their businesses, including an awareness of the financial impact generated by corporate environmental performance. “Justifying the investment,” as stated by Interviewee B, may be the key idea at this moment.

Beyond the socio-environmental benefits and the imperative need to reshape business models into circular, sustainable, and environmentally ethical structures, environmental management also constitutes a powerful business strategy. It incorporates risk reduction and opportunity capture in building more competitive companies aligned with the global environmental requirements of corporations, governments, and modern societies. Overall, managers’ perceptions of the impact of environmental performance on financial outcomes highlight a growing integration between these dimensions in corporate strategies. The following section presents the final considerations of the study.

5 FINAL CONSIDERATIONS

This study aimed to analyze the influence of environmental performance on financial performance, focusing methodologically on companies listed in the ISE between 2022 and 2024. To meet the proposed objectives, the research was divided into two methodological phases: the first quantitative and the second qualitative. These phases led to the conclusion that corporate environmental performance is important not only for society and the environment but also for the financial performance of businesses.

During the first stage of the research, a statistically significant though low in magnitude and practical effect influence of environmental performance on the financial performance of listed companies was found, with emphasis on the impact of environmental dimensions on the ROE of companies. The findings of this stage corroborate previous analyses showing benefits arising from improvements in environmental performance for companies’ financial results. Nevertheless, it is confirmed that only some financial indicators showed a statistically significant influence from environmental indicators, with emphasis on the low predictive power. The low magnitude of statistical coefficients may reflect a national and global context marked by the complexity of corporate efforts to reconcile environmental needs with financial results. Although modest in practical effect, the positive and significant direction identified may indicate a future scenario in which environmental performance will have a greater impact on the financial performance of listed companies.

The second stage showed that company managers already recognize the impact that environmental management practices have on corporate financial performance and business sustainability, with emphasis on the financial risks and opportunities related to the environmental agenda in the organizational context. Multi-level environmental management practices, involving companies, governments, and civil society, were highlighted as a powerful tool for developing increasingly integrated strategies that align financial and environmental objectives in corporate management.

Insights from the interviews, which corroborate the quantitative phase, revealed that analyzing the relationship between financial and environmental performance should go beyond merely identifying positive correlations. It should also address the concept of integrating these indicators as a business opportunity and a competitive advantage an approach that has proven essential for companies’ prosperity in a market increasingly influenced by values grounded in the pillars of sustainability.

The research makes relevant contributions to understanding the complex and dynamic relationship between environmental management and financial performance in the context of the capital market, and more specifically, among companies participating in Brazil’s main sustainability index. The study therefore presents theoretical implications by clarifying the state of the art regarding the relationship between financial and environmental performance in the contexts of emerging economies’ capital markets, the Brazilian Stock Exchange, and the ISE. The combination of quantitative and qualitative phases sought to deepen previous discussions in the literature on the impact of environmental performance on financial performance. The scarcity of qualitative studies identified in the literature on the topic reinforces the importance of integrating this stage into the quantitative phase, allowing an understanding through practical examples of how environmental performance can improve financial performance, consistent with what was found, albeit still in an emerging way, in the regression modeling. Similarly, it presents managerial implications by identifying emerging trends of positive influence from environmental performance on corporate financial results.

Despite the contributions highlighted, the study has some limitations. First, it is important to note that the quantitative stage was limited to three years of data, which did not allow for a longitudinal analysis. Future studies with a larger dataset are recommended to apply Multivariate Analysis of Variance (MANOVA) to evaluate the evolution of environmental and social performance dimensions of the ISE over time, which could reveal the progression of listed companies as the index and its evaluation criteria mature and gain greater prominence. Furthermore, comparative analyses between the Brazilian capital market and other more or less developed economies could be useful in discussing the relationship between the core constructs under study. Considering the specific characteristics of different economic activity sectors which generate distinct environmental impacts and face different environmental and financial challenges may also be relevant for future research.

In addition, the small number of interviewed managers may be a limitation of the study, as despite the importance of their positions and the recognized difficulty of obtaining responses from senior executives in publicly traded companies, conducting only two interviews may not have captured other relevant information for the research, which could, in turn, influence the conclusions. Furthermore, focusing the interviews exclusively on managers’ perceptions may also constitute a limitation. Future research is recommended to apply similar analyses with managers as well as other stakeholders involved in the decision-making process across all sectors represented in the ISE, in order to understand the congruences and divergences in their perceptions of the relationship between financial performance and the environmental agenda in the corporate context. Finally, studies comparing the perceptions of managers from Brazilian companies with those from international companies could provide important insights into the stage of development of environmental awareness in Brazil’s corporate sector compared with other countries.

Environmental issues including water scarcity, air, water, and soil pollution, competition for increasingly scarce natural resources, and extreme weather events that have destroyed entire cities and significantly impacted the corporate environment are an unavoidable reality for companies. The pursuit of profit, return, and financial results, especially in the current context of economic crisis and high market competitiveness, is also a reality from which companies cannot abstain. Therefore, in a world increasingly influenced by socio-environmental demands, companies that develop and implement management systems integrating environmental practices with financial metrics represent the business model expected for the present sustainable, profitable, and environmentally responsible.

Material suplementario
Información adicional

redalyc-journal-id: 5707

REFERENCES
Ahmed, S. K. (2025). Sample size for saturation in qualitative research: Debates, definitions, and strategies. Journal of Medicine, Surgery, and Public Health, 5, 1-6. https://doi.org/10.1016/j.glmedi.2024.100171
Almada, L., & Borges, R. (2018). Sustainable competitive advantage needs green human resource practices: A framework for environmental management. Revista de Administração Contemporânea, 22(3), 424-442. https://doi.org/10.1590/1982-7849rac2018170345
Almada, L., Borges, R. S. G., & Ferreira, B. P. (2022). As estratégias da visão baseada em recursos naturais são lucrativas? um estudo longitudinal do índice de sustentabilidade empresarial brasileiro. Revista Brasileira de Gestão de Negócios, 24(3), 533-555. https://doi.org/10.7819/rbgn.v24i3.4185
Amarasuriya, S., Burke, G., & Hsu, T. K. (2024). Operational competitiveness and the relationship between corporate environmental and financial performance. Journal of Risk and Financial Management, 17(364), 1–17. https://doi.org/10.3390/jrfm17080364
Arteaga, E., Nalau, J., Biesbroek, R., & Howes, M. (2023). Unpacking the theory-practice gap in climate adaptation. Climate Risk Management, 42, 1–16. https://doi.org/10.1016/j.crm.2023.100567
B3 S.A. – Brasil, Bolsa, Balcão. (2022). ISE B3 2022 (Carteira 2023). https://esgworkspace.b3.com.br/dashboard
B3 S.A. – Brasil, Bolsa, Balcão. (n.d.). Índice de Sustentabilidade Empresarial (ISE B3). https://www.b3.com.br/pt_br/market-data-e-indices/indices/indices-de-sustentabilidade/indice-de-sustentabilidade-empresarial-ise-b3.htm
Baah, C., Opoku-Agyeman, D., Acquah, I. S. K., Agyabeng-Mensah, Y., Afum, E., Faibil, D., & Abdoulaye, F. A. M. (2021). Examining the correlations between stakeholder pressures, green production practices, firm reputation, environmental and financial performance: Evidence from manufacturing SMEs. Sustainable Production and Consumption, 27, 100–114. https://doi.org/10.1016/j.spc.2020.10.015
Bodgan, V., Rus, L., Gherai, D. S., Florea, A. G., & Bugnar, N. G. (2023). A streamline sustainable business performance reporting model by an integrated FinESG approach. Sustainability, 15, 1–25. https://doi.org/10.3390/su152416860
Braunerhjelm, P., & Hepburn, C. (2023). Climate change, complexity, and policy design. Oxford Review of Economic Policy, 39, 667–679. https://doi.org/10.1093/oxrep/grad047
Cassepp-Borges, V., Balbinotti, M. A. A., & Teodoro, M. L. M. (2010). Tradução e validação de conteúdo: Uma proposta para a adaptação de instrumentos. In L. Pasquali (Org.), Instrumentação psicológica: Fundamentos e práticas (pp. 506-520). Artmed.
Castilho, A. R. B., & Barakat, S. R. (2022). The relationship between climate change mitigation strategies and the financial performance of Brazilian companies. Journal of Industrial Ecology, 26, 1294-1305. https://doi.org/10.1111/jiec.13265
Cavaco, S., & Crifo, P. (2014). CSR and financial performance: Complementarity between environmental, social and business behaviours. Applied Economics, 46(27), 3323-3338. https://doi.org/10.1080/00036846.2014.927572
Chowdhury, S. B., Dasgupta, R., Chowdhury, B. K., & Sen, N. (2023). Evolving alliance between corporate environmental performance and financial performance: A bibliometric analysis and systematic literature review. Business and Society Review, 128(1), 95-131. https://doi.org/10.1111/basr.12301
Cornellissen, T., & Mukwarami, S. (2024). Examining the relationship between environmental management accounting practices and return on equity in the South African chemical industry. Environmental Economics, 15(1), 190–202. https://doi.org/10.21511/ee.15(1).2024.14
Creswell, J. W. (2007). Qualitative inquiry and research design: Choosing among five approaches. 2 ed. Sage Publications.
Diez, N. R., Cuervo, C. M., & Parra, M. A. (2023). Exploring the asymmetric impact of sustainability reporting on financial performance in the utilities sector: A longitudinal comparative analysis. Utilities Policy, 84, 1–12. https://doi.org/10.1016/j.jup.2023.101650
Donohue, W. O., & Torugsa, N. A. (2016). The moderating effect of ‘green’ HRM on the association between proactive environmental management and financial performance in small firms. The International Journal of Human Resource Management, 27(2), 239-261. https://doi.org/10.1080/09585192.2015.1063078
Endrikat, J., Guenther, E., & Hoppe, H. (2014). Making sense of conflicting empirical findings: A meta-analytic review of the relationship between corporate environmental and financial performance. European Management Journal, 32, 735-751. https://doi.org/10.1016/j.emj.2013.12.004
Feng, M., Yu, W., Wang, X., Wong, C. Y., Xu, M., & Xiao, Z. (2018). Green supply chain management and financial performance: The mediating roles of operational and environmental performance. Business Strategy and the Environment, 27, 811–824. https://doi.org/10.1002/bse.2033
Garcia, M. P. R., Manrique, A. F. G., Alejandro, K. A. C., & Saenz, A. B. M. (2022). Eco-efficiency and financial performance in Latin American countries: An environmental intensity approach. Research in International Business and Finance, 59, 1–10. https://doi.org/10.1016/j.ribaf.2021.101547
Gasbarro, F., Iraldo, F., & Daddi, T. (2017). The drivers of multinational enterprises’ climate change strategies: A quantitative study on climate-related risks and opportunities. Journal of Cleaner Production, 160, 8–26. https://doi.org/10.1016/j.jclepro.2017.03.018
Gholami, A., Murray, P. A., & Sands, J. (2022). Environmental, social, governance & financial performance disclosure for large firms: Is this different for SME firms? Sustainability, 14(10), 6019, 2–21. https://doi.org/10.3390/su14106019
Grisales, E. D., & Caracuel, J. A. (2021). Environmental, social and governance (ESG) scores and financial performance of multilatinas: Moderating effects of geographic international diversification and financial slack. Journal of Business Ethics, 168, 315–334. https://doi.org/10.1007/s10551-019-04177-w
Guirk, P. M., Downling, R., & Carr, C. (2019). The material politics of smart building energy management: A view from Sydney's commercial office space. Political Geography, 74, 1–10. https://doi.org/10.1016/j.polgeo.2019.102034
Harif, A., & Natasha, P. (2024). A review on green accounting practices and sustainable financial performance. Journal of Business Management and Information Systems, 11, 82–88. https://doi.org/10.48001/jbmis.2024.si1015
Haukos, J. S., & Lewis, R. J. (2005). Advanced statistics: Bootstrapping confidence intervals for statistics with “difficult” distributions. Academic Emergency Medicine, 12(4), 360-365. https://doi.org/10.1197/j.aem.2004.11.018
Hristov, I., Appolloni, A., & Chirico, A. (2022). The adoption of the key performance indicators to integrate sustainability in the business strategy: A novel five-dimensional framework. Business Strategy and the Environment, 31, 3216–3230. https://doi.org/10.1002/bse.3072
Hu, J., & Zhao, Y. (2024). Improving corporate profitability from the inside out with environmental performance: An empirical analysis based on Chinese listed company data. Frontiers in Environmental Science, 12, 1–18. https://doi.org/10.3389/fenvs.2024.1489896
Ismail, A. M., & Azman, K. B. B. (2024). The impact of environmental, social, and governance performance on financial performance: Evidence from Japanese companies. Edelweiss Applied Science and Technology, 8(3), 236–258. https://doi.org/10.55214/25768484.v8i3.950
Kouloukoui, D., Sant’anna, A. M. O., Gomes, S. M. S., Marinho, M. M. O., Jong, P., Kiperstok, A., & Torres, E. A. (2019). Factors influencing the level of environmental disclosures in sustainability reports: Case of climate risk disclosure by Brazilian companies. Corporate Social Responsability and Environmental Management, 26, 791-804. https://doi.org/10.1002/csr.1721
Lee, M. T., & Raschke, R. L. (2023). Stakeholder legitimacy in firm greening and financial performance: What about greenwashing temptations? Journal of Business Research, 155, 1–11. https://doi.org/10.1016/j.jbusres.2022.113393
Li, D., Cao, C., Zhang, L., Chen, X., Ren, S., & Zhao, Y. (2017). Effects of corporate environmental responsibility on financial performance: the moderating role of government regulation and organizational slack. Journal of Cleaner Production, 166, 1323-1334. https://doi.org/10.1016/j.jclepro.2017.08.129
Lima, C. R. M., Barbosa, S. B., Sobrosa, R. C., Neto, Bazil, D. G., & Guerra, J. B. S. O. A. (2022). Corporate financial performance: A study based on the Carbon Efficient Index (ICO₂) of Brazil Stock Exchange. Environment, Development and Sustainability, 24, 4323–4354. https://doi.org/10.1007/s10668-021-01617-4
Liu, G., Yang, J., Hao, Y., & Zhang, Y. (2018). Big data-informed energy efficiency assessment of China industry sectors based on K-means clustering. Journal of Cleaner Production, 183, 304–314. https://doi.org/10.1016/j.jclepro.2018.02.129
Lucas, E. C., Yoshikuni, A. C., & Agustini, C. A. (2022). Relação de causalidade entre os índices de sustentabilidade empresarial e Ibovespa no Brasil. Reunir: Revista de Administração, Contabilidade e Sustentabilidade, 12(3), 30-42. https://doi.org/10.18696/reunir.v12i3.1476
Lucato, W. C., Costa, E. M., & Oliveira, G. C., Neto. (2017). The environmental performance of SMEs in the Brazilian textile industry and the relationship with their financial performance. Journal of Environmental Management, 203, 550–556. https://doi.org/10.1016/j.jenvman.2017.06.028
Lüdecke, D., Ben-Shachar, M., Patil, I., & Makowski, D. (2020). Extracting, computing and exploring the parameters of statistical models using R. Journal of Open Source Software, 5(53), 2445. https://doi.org/10.21105/joss.02445
Lutzer, A. V. B., Britto, L. P. S., Nascimento, I. J. B. M. F., Moraes, L. C. N., Carvalho, A. P., Moraes, A. S., Marques, F. R. V., Amaral, R. A., & Marques, I. C. (2024). Business management and environmental, social and corporate governance: The tripod of sustainability in organizations. Revista de Gestão Social e Ambiental, 18(8), 1–12. https://doi.org/10.24857/rgsa.v18n8-200
McCarthy, M. A., Thompson, C. J., Hauser, C., Burgman, M. A., Possingham, H. P., Moir, M. L., Tiensin, T., & Gilbert, M. (2010). Resource allocation for efficient environmental management. Ecology Letters, 13, 1280–1289. https://doi.org/10.1111/j.1461-0248.2010.01522.x
Moçato, E., Melo, M. F. S., Campos, W. L., & Polo, E. F. (2019). The business of the business is not just the business: business sustainability as strategic element. Revista de Administração da UFSM, 12(1), 41–53. https://doi.org/10.5902/1983465917339
Moraes, R. (1999). Análise de conteúdo. Revista Educação, 22(37), 7-32.
Murphy, R. (2024). What is undermining climate change mitigation? How fossil-fuelled practices challenge low-carbon transitions. Energy Research & Social Science, 108, 1–11. https://doi.org/10.1016/j.erss.2023.103390
Nações Unidas Brasil. (2021). É preciso refletir o 'verdadeiro valor' da natureza nas políticas e decisões econômicas, diz chefe da ONU.https://brasil.un.org/pt-br/114549-%C3%A9-preciso-refletir-o-verdadeiro-valor-da-natureza-nas-pol%C3%ADticas-e-decis%C3%B5es-econ%C3%B4micas-diz
Santos, M. I. C., Leite, P. A. M., Filho, & Santos, M. L. C. (2021). Sustentabilidade e Desempenho Econômico-Financeiro: análise de aderência ao Índice de Sustentabilidade Empresarial (ISE). Revista de Administração, Contabilidade e Economia da Fundace, 12(3), 39-55. https://doi.org/10.13059/racef.v12i3.737
Schmuller, J. (2019). Análise estatística com R. 2. ed. Alta Books.
Schober, P., Boer, C., & Schwarte, L. A. (2018). Correlation coefficients: Appropriate use and interpretation. Anesthesia & Analgesia, 126(5), 1763-1768. https://doi.org/10.1213/ANE.0000000000002864
Severo, E. A., Guimarães, J. C. F., & Dorion, E. C. H. (2017). Cleaner production and environmental management as sustainable product innovation antecedents: A survey in Brazilian industries. Journal of Cleaner Production, 142, 87-97. https://doi.org/10.1016/j.jclepro.2016.06.090
Silva, V. M., & Lucena, W. G. L. (2019). Contabilidade ambiental: análise da participação no índice de sustentabilidade empresarial (ISE) e a rentabilidade das empresas listadas na [B]3. Revista Gestão & Tecnologia, 19(2), 109-125. https://doi.org/10.20397/2177-6652/2019.v19i2.1563
Sim, J., Saunders, B., Waterfield, J., & Kingstone, T. (2018). Can sample size in qualitative research be determined a priori? International Journal of Social Research Methodology, 21(5), 619-634. https://doi.org/10.1080/13645579.2018.1454643
Sobrosa, R. C., Neto, Lima, C. R. M., Bazil, D. G., Veras, M. O., & Guerra, J. B. S. O. A. (2020). Sustainable development and corporate financial performance: A study based on the Brazilian Corporate Sustainability Index (ISE). Sustainable Development, 28, 960-977. https://doi.org/10.1002/sd.2049
Tan, K., Siddik, A. B., Sobhani, F. A., Hamayun, M., & Masukujjaman, M. (2022). Do environmental strategy and awareness improve firms’ environmental and financial performance? The role of competitive advantage. Sustainability, 14, 1–24. https://doi.org/10.3390/su141710600
Wang, S., Xing, L., Chen, X., & Song, M. (2024). Evaluating and enhancing natural resource asset management efficiency in China: A data envelopment analysis study. Resources Policy, 92, 1-12. https://doi.org/10.1016/j.resourpol.2024.105000
Xie, J., Nozawa, W., Yagi, M., Fujii, H., & Managi, S. (2019). Do environmental, social, and governance activities improve corporate financial performance? Business Strategy and the Environment, 28, 286–300. https://doi.org/10.1002/bse.2224
Zago, A. P. P., Jabbour, C. J. C., & Bruhn, N. C. P. (2018). Sustentabilidade corporativa e criação de valor: O caso “Dow Jones Sustainability Index”. Gestão & Produção, 25(3), 531–544. https://doi.org/10.1590/0104-530X2958-16
Zhang, K. Q., & Chen, H. H. (2017). Environmental performance and financing decisions impact on sustainable financial development of Chinese environmental protection enterprises. Sustainability, 9, 1–14. https://doi.org/10.3390/su9122260
Zhang, Y. (2021). Influence of resource mismatch between industries on environmental efficiency. Advances in Economics, Business and Management Research, 186, 1–8. https://doi.org/10.2991/aebmr.k.210809.007
Notas

Figure 1
Stages of the quantitative phase
Source: Developed by the authors.

Figure 2
Technical procedures (multiple regressions)
Source: Developed by the authors.
Table 1
Categories of analysis and study topics.

Source: Developed by the authors.
Table 2
Pearson correlation analyses between environmental and financial variables

Source: Research data.Note: * = p < 0,05; ** = p < 0,01.
Table 3
Predictor variables of the financial performance variable ROA

Source: Research data.Note: * = p < 0,05; ** = p < 0,01.
Table 4
Predictor variables of the financial performance variable ROE

Source: Research data.Nota: * = p < 0,05; ** = p < 0,01.
Table 5
Summary of companies participating in the qualitative stage

Source: Research data.* Values in R$ 1,000 (thousand Brazilian reais), rounded to three decimal places. The values are presented approximately in millions of Brazilian reais to preserve the anonymity of the companies.
Table 6
Summary of interviewees

Source: Research data.
Buscar:
Contexto
Descargar
Todas
Imágenes
Visor de artículos científicos generados a partir de XML-JATS por Redalyc